CONTROL CENTER
50%
Read of the day
Neutral, subjective 50%, not a calibrated win rate. Futures are mixed as bank earnings start: JPMorgan missed on EPS ($5.57 vs $5.93 expected), Wells Fargo beat on EPS ($1.87 vs $1.85) but missed on revenue, and Goldman, Citi, J&J and UnitedHealth also report. A global AI and chip selloff weighs on tech. The 10-year yield is about 5.19%, down roughly 5.5 bp, the dollar is near an 18-month high and Fed speakers lean hawkish. Brent is about $105.7. Existing Home Sales are at 10:00 AM, September CPI is Wednesday, PPI and retail sales Thursday. MES overnight swept Monday's low, reclaimed it, ran to 7,864 at 6:05 AM and faded back to about 7,850. Price sits between Monday's RTH low 7,846.25 and the bearish gaps overhead. No breakers, no rule changes.
Liquidity map
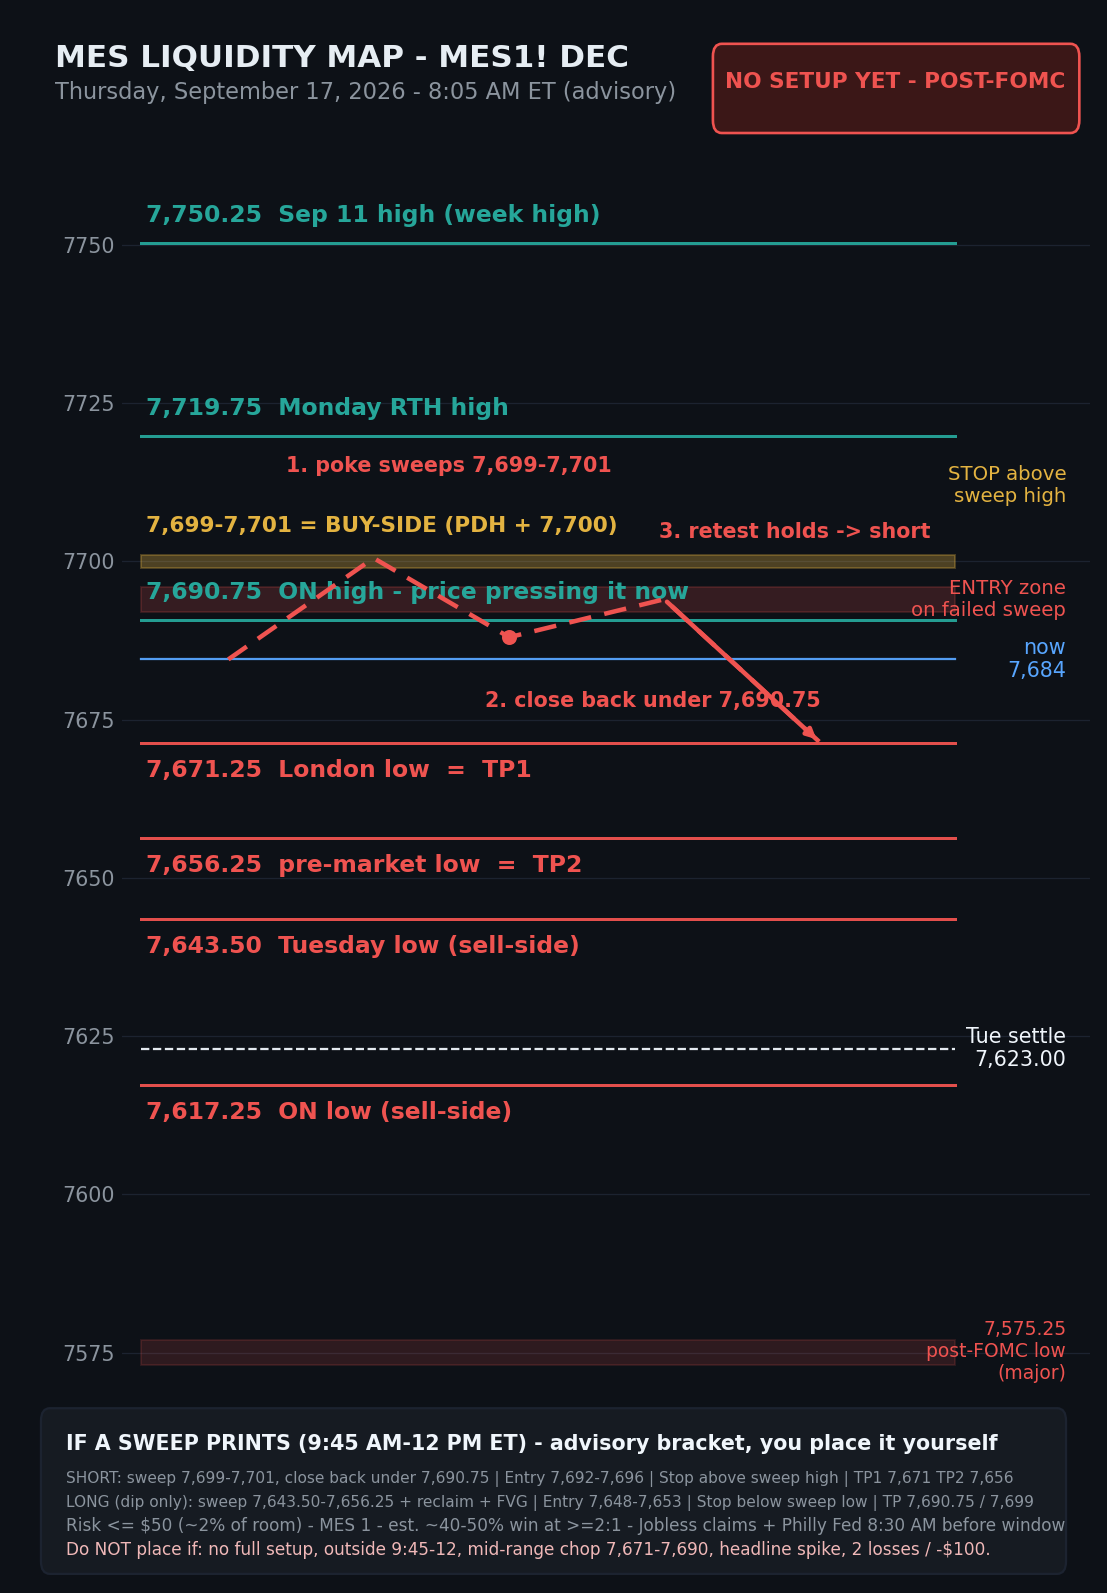
Live chart - S&P 500 proxy (NOT MES1!)
Tape setup
MES own levels: Mon RTH high 7,870.00, low 7,846.25, close 7,856.75. Fri RTH high 7,870.75, low 7,826.50. Overnight (6 PM on) high 7,864.00, low 7,835.75. Unfilled bearish gaps above: 7,857.75-7,861.50 and 7,851.75-7,857 (15m), 7,854.50-7,856.25 (1H), 7,873-7,878 (15m/1H). Bullish gap below: 7,843.50-7,847.50 (15m). BUY SIDE = highs above price (7,864, 7,870, 7,870.75); SELL SIDE = lows below price (7,846.25, 7,835.75, 7,826.50). The dated drawdown-room figure and the delayed bars are context, not execution facts.
Catalysts
Bank earnings today: JPMorgan (missed EPS), Wells Fargo (beat EPS, missed revenue), Goldman, Citi, plus J&J and UnitedHealth. 10:00 AM ET Existing Home Sales. Treasury market reopens after Columbus Day with the 10-year near 5.19%. Oil: Brent about $105.7. Wednesday: September CPI. Thursday: PPI and retail sales.
Sources and freshness
Dow Jones morning briefing · MarketWatch bank earnings · TipRanks futures · FXStreet
The play - conditional sweep setups, both sides (you place it, you own it)
Guardrails
Advisory only. Frozen caps $50 long / $25 short, minimum 2R, max two trades/day, stop after two losses or -$100. No entry is active until the conditions above print. Broker/account internals omitted from this shared briefing.
Journal - Kilo
Journal - Anthony
What's new
- Audit - Friday page published 7:55 AM with the Oct 9 bracket card. Snapshot: 7:45 AM feed, price ~7,847. Rebuilt the page API worker from its saved source after a workspace reset; price, bars and journal outputs checked identical before switching. Fri Oct 9 AM ET
- Audit - Monday page published 7:55 AM; no setup printed yet. Snapshot: 7:50 AM feed, price ~7,779. Rebuilt the page's API worker after a workspace reset; price, bars and journal outputs were checked identical to the prior ones before switching, and the existing journal entries are intact. Fixed a stale Project X loss figure left in Friday's text (-$189.60 is now -$184.60 per the Oct 2 cost correction). Mon 7:55 AM ET
- Audit - Friday page published 8:05 AM with the NFP-day bracket card. Snapshot: 7:52 AM Tradovate live, price ~7,757. Also repaired the page header (the Thursday publish had left the HTML doctype overwritten and a stale Wednesday date in the header). Fri 8:05 AM ET
- Audit - Thursday page published 8:05 AM with the ISM-day bracket card. Snapshot: 7:52 AM Tradovate live, price ~7,742.25. Thu 8:05 AM ET
- Audit - Wednesday page published 8:00 AM with the PCE-day bracket card. Snapshot: 7:55 AM feed, price ~7,732. Wed 8:00 AM ET
- Audit - Stripped an unverified attribution from the old Tue 7:10 AM change-log entry; the log only keeps requests that can be verified. Tue 8:05 AM ET
- Audit - Tuesday page published early at 7:10 AM; folded into the usual morning build. Snapshot: 7:05 AM feed, price ~7,842.50. Tue 7:10 AM ET
- Audit - Triple-check correction: 7,750.25 was mislabeled "week high" - it is last Friday's (Sep 11) high; this week's high is 7,739.00 (= ON high). Level itself unchanged. Fri 8:20 PM ET
- Kilo - "Start using MES1!": every level, the price strip, the chart, and alerts switched from the September contract to MES1! (December). Live Sep-Dec spread verified at 67.00 before translating. Tue 10:40 AM ET
- Kilo - Liquidity map cleaned up: targets merged into their levels (Friday high = TP1, range top = TP2), no more overlapping labels, staggered text, stop and settle moved to the side rail. Sun 11:41 PM ET
- Anthony - "Change the market to MES": market toggle now reads MES / MNQ (the micros actually traded here) and the page is denominated in MES throughout. Sun 10:31 PM ET
- Kilo - Trading Plan rulebook added as a permanent section. Sun 10:13 PM ET
- Kilo - Site goes interactive: live price, zoomable chart, took-it/skipped-it journal buttons, ES/NQ toggle. Sun 10:30 PM ET
- Kilo - Automatic trade journaling: executed trades pulled after each session and scored against the rulebook. Sun 10:30 PM ET
- Kilo - Separate journals for Kilo and Anthony, both interactive. Sun 10:30 PM ET
The Trading Plan
- MES only, 1 contract. No other symbols, no adds.
- 1-2 trades per day. When they're used, the day is done.
- Window: premarket, or after the first 15m candle post-9:30 (from ~9:45 AM ET).
- Risk cap is the setup filter: MES stop of 10 pts ($50) or less = legal trade. A wider stop means the setup gets skipped, not sized up. Cap scales with drawdown room.
- Shorts only on the full setup (sweep + close back inside + structure shift + FVG fill), $25 risk.
- Daily stop: two losses or -$100, whichever comes first.
- No MYM or MNQ until MES produces two profitable weeks.
- Journal every trade against the setup, win or lose.